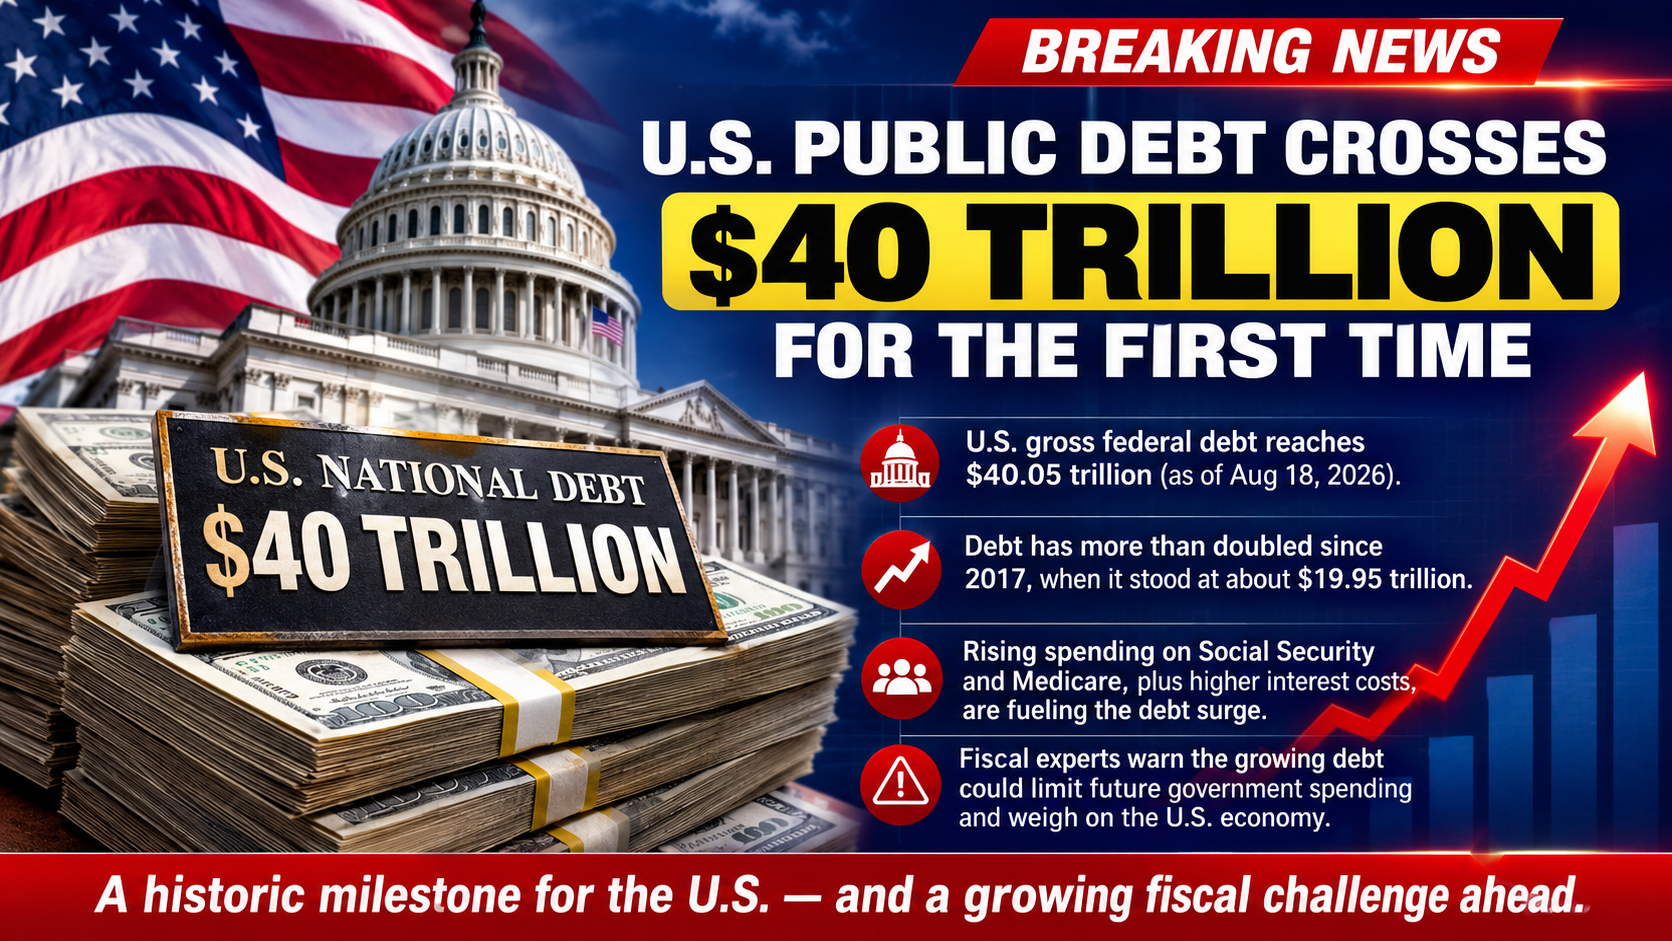
The United States has reached a historic and sobering fiscal milestone, with the nation’s total public debt officially surpassing $40 trillion for the first time.
According to U.S. Treasury data, gross federal debt stood at approximately $40.05 trillion as of August 18, 2026. The milestone comes just five months after the debt crossed $39 trillion, highlighting the rapid pace at which federal borrowing has increased.
Of the total, about $32.3 trillion is held by the public, while roughly $7.8 trillion consists of intragovernmental holdings. The debt has more than doubled since 2017, when it stood at around $19.95 trillion.
Rising spending on programs including Social Security and Medicare, along with rapidly increasing interest costs, has contributed significantly to the growing debt burden. The federal government is also continuing to run large annual budget deficits, with the United States borrowing about $1.8 trillion during the first 10 months of fiscal year 2026, according to the Committee for a Responsible Federal Budget.
The growing cost of servicing the debt is becoming an increasingly important concern. Interest payments have risen sharply as debt levels and borrowing rates increase, putting additional pressure on the federal budget and potentially limiting funds available for other government priorities.
The $40 trillion milestone is largely symbolic, but economists and fiscal experts say the underlying trend is significant. The Congressional Budget Office has projected that debt held by the public could continue rising substantially over the coming decade if current fiscal policies remain largely unchanged.
The record debt level is now intensifying debate in Washington over government spending, taxation, entitlement programs and long-term fiscal sustainability. The challenge for policymakers will be finding a way to slow the growth of federal debt without causing major disruptions to the U.S. economy.